Generating Random Variates From An Inverse-Gaussian Distribution
The following algorithm may be used.
Generate a random variate from a normal distribution with a mean of 0 and 1 standard deviation
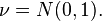
Square the value

and use this relation

Generate another random variate, this time sampled from a uniformed distribution between 0 and 1
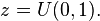
If

then return

else return

Sample code in Java:
public double inverseGaussian(double mu, double lambda) { Random rand = new Random; double v = rand.nextGaussian; // sample from a normal distribution with a mean of 0 and 1 standard deviation double y = v*v; double x = mu + (mu*mu*y)/(2*lambda) - (mu/(2*lambda)) * Math.sqrt(4*mu*lambda*y + mu*mu*y*y); double test = rand.nextDouble; // sample from a uniform distribution between 0 and 1 if (test <= (mu)/(mu + x)) return x; else return (mu*mu)/x; }Read more about this topic: Inverse Gaussian Distribution
Famous quotes containing the words random and/or distribution:
“Assemble, first, all casual bits and scraps
That may shake down into a world perhaps;
People this world, by chance created so,
With random persons whom you do not know—”
—Robert Graves (1895–1985)
“My topic for Army reunions ... this summer: How to prepare for war in time of peace. Not by fortifications, by navies, or by standing armies. But by policies which will add to the happiness and the comfort of all our people and which will tend to the distribution of intelligence [and] wealth equally among all. Our strength is a contented and intelligent community.”
—Rutherford Birchard Hayes (1822–1893)