Definition
Assume that we are regressing the linear regression model

where X is the design matrix and β is a k × 1 column vector of parameters to be estimated.
The ordinary least squares (OLS) estimator is
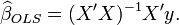
If the sample errors have equal variance σ2 and are uncorrelated, then the least-squares estimate of β is BLUE (best linear unbiased estimator), and its variance is easily estimated with
where are regression residuals.
When the assumptions of are violated, the OLS estimator loses its desirable properties. Indeed,
where .
While the OLS point estimator remains unbiased, it is not "best" in the sense of having minimum mean square error, and the OLS variance estimator does not provide a consistent estimate of the variance of the OLS estimates.
Read more about this topic: Heteroscedasticity-consistent Standard Errors
Famous quotes containing the word definition:
“I’m beginning to think that the proper definition of “Man” is “an animal that writes letters.””
—Lewis Carroll [Charles Lutwidge Dodgson] (1832–1898)
“According to our social pyramid, all men who feel displaced racially, culturally, and/or because of economic hardships will turn on those whom they feel they can order and humiliate, usually women, children, and animals—just as they have been ordered and humiliated by those privileged few who are in power. However, this definition does not explain why there are privileged men who behave this way toward women.”
—Ana Castillo (b. 1953)
“No man, not even a doctor, ever gives any other definition of what a nurse should be than this—”devoted and obedient.” This definition would do just as well for a porter. It might even do for a horse. It would not do for a policeman.”
—Florence Nightingale (1820–1910)