The Model
Suppose there are m regression equations

Here i represents the equation number, and t = 1, …, T is the observation index. The number of observations is assumed to be large, so that in the analysis we take T → ∞, whereas the number of equations m remains fixed.
Each equation i has a single response variable yit, and a ki-dimensional vector of regressors xit. If we stack observations corresponding to the i-th equation into T-dimensional vectors and matrices, then the model can be written in vector form as
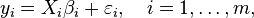
where yi and εi are T×1 vectors, Xi is a T×ki matrix, and βi is a ki×1 vector.
Finally, if we stack these m vector equations on top of each other, the system will take form
-

(1)
The assumption of the model is that error terms εit are independent across time, but may have cross-equation contemporaneous correlations. Thus we assume that E = 0 whenever t ≠ s, whereas E = σij. Denoting Σ = ] the m×m skedasticity matrix of each observation, the covariance matrix of the stacked error terms ε will be equal to
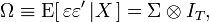
where IT is the T-dimensional identity matrix and ⊗ denotes the matrix Kronecker product.
Read more about this topic: Seemingly Unrelated Regressions
Famous quotes containing the word model:
“There are very many characteristics which go into making a model civil servant. Prominent among them are probity, industry, good sense, good habits, good temper, patience, order, courtesy, tact, self-reliance, many deference to superior officers, and many consideration for inferiors.”
—Chester A. Arthur (1829–1886)
“I’d like to be the first model who becomes a woman.”
—Lauren Hutton (b. 1944)